
A dental practice loan is sized by cash flow, not by the price on the listing. Take what the practice earns after paying you a market salary for your dentistry, divide it by a coverage ratio (the SBA requires at least 1.25 for a first acquisition), and the result is the yearly payment you can carry. The loan, your equity and the lender’s valuation then set the price you can afford.
- For an SBA 7(a) initial acquisition, the practice’s historical earnings must cover all post-closing debt payments at least 1.25 times. Projections can’t be used to meet that test (SBA SOP 50 10 8.1, effective October 1, 2026).
- Total debt is capped at the lender’s business valuation, and you bring at least 10% of the project cost as equity. A seller note on full standby can cover no more than half of that 10%.
- The lender’s maximum is a ceiling, not a target. Your own test adds your living costs and student loans; the ADEA reports average education debt of $297,800 for 2025 graduates with debt.
- Loan principal isn’t deductible. Goodwill is deducted over 15 years while most acquisition loans run 10, so part of every payment comes out of income you’ve already paid tax on.
- What we see with buyers: the bank’s number gets checked carefully, while the after-tax cash left for the owner in years two to five gets checked last.
The lender came back with a pre-approval that’s bigger than you expected. The broker says the practice you like “fits right inside it.” Before you sign anything, the useful question isn’t whether the bank will lend. It’s whether the practice will pay the loan and you, every month, after tax, for the next ten years.
This guide walks through dental practice financing the way it gets decided: how lenders size the loan, how much of it the practice can carry, and the tax rules that change what each payment really costs.
What is a dental practice loan, and what isn’t it?
A dental practice acquisition loan is a term loan, usually about ten years, that funds the purchase of a practice’s goodwill, patient base, equipment and often working capital, repaid from the practice’s cash flow. Most come from banks with dental lending teams, either as a conventional practice loan or as an SBA 7(a) loan, where the SBA backs part of the loan for the lender. The 7(a) maximum is $5 million, and the same loan can fund a change of ownership, equipment and working capital (SBA).
It gets confused with other kinds of debt that follow different rules:
| What it pays for | Typical term | How it’s sized | |
|---|---|---|---|
| Practice acquisition loan (conventional or SBA 7(a)) | Goodwill, equipment, working capital | About 10 years; the SBA caps it at 10 unless real estate or long-life equipment is financed | Practice cash flow, the lender’s valuation, your equity |
| Seller note | Part of the price, owed to the seller | Negotiated | What the seller will carry and the lender allows |
| Equipment financing | A specific unit (CBCT, chairs, a scanner) | Matched to the equipment’s life | The equipment’s value and your credit |
| Commercial real estate loan | The building | Up to 25 years under 7(a) | Property value and rent the practice can pay |
| Line of credit | Short-term gaps in cash | Revolving | Receivables and the practice’s history |
SBA maturity limits come from the program’s terms: ten years or less unless the loan finances real estate or equipment with a longer useful life, and a maximum of 25 years (SBA). Whether to buy the building is its own decision, with its own math.
Who is this math for, and who can skip it?
It’s for any dentist about to borrow for a practice: first purchase, second location or partner buy-in. The situations we hear about most:
- An associate with a pre-approval letter, comparing two practices listed at very different prices.
- An owner adding a second location, where the new payment sits on top of the first practice’s debt.
- A buyer whose seller offered to carry part of the price on a note.
- An associate offered a buy-in, with financing the owner’s bank already lined up.
You can skip most of this if you’re buying with cash, or if you’re still two or more years from looking. In that case, start with what a practice is worth, covered in our dental practice valuation guide, and come back when there’s a real practice on the table.
Why does the loan size matter more than the price?
Because the payment is fixed for years, while collections, fees and staff costs move. An acquisition loan is usually repaid in equal monthly payments of principal and interest from the practice’s cash flow (SBA). If you overpay by a little, a ten-year loan turns that into a monthly payment you carry through every slow quarter.
It also stacks on debt you already have. The ADEA reports that 2025 dental graduates with education debt owed $297,800 on average (ADEA, Dentists of Tomorrow 2025). The SBA asks lenders to test that the owners’ pay covers their personal obligations too, at 1 to 1 on a global basis (SBA SOP 50 10 8.1). The practice loan, your student loans and your household all draw on the same cash.
When should you run the numbers, and when is it too late?
Run them before you make an offer, and rerun them before the letter of intent. Once the price and terms are in a signed letter, the loan simply follows the deal.
- Before you look at listings: talk to at least three lenders who finance dental practices, as the ADA suggests, and learn how each one sizes a loan.
- Before the offer: run the coverage test on the practice’s last full year and the two-year average, after a market salary for you.
- Before the letter of intent: settle how much cash you’ll put in, whether the seller carries a note, and what the payment leaves you after tax.
- Before closing: open the account the loan money will flow through, and set up payroll so your own salary is real from day one.
If you’re closing on a practice, come before the closing, not after. The structure decisions happen at the table. The full order of steps is in what to check before you sign for a practice.
How lenders size a dental practice loan
Three tests decide the number: debt coverage, the valuation cap and your equity. Conventional dental lenders set their own versions. The SBA spells its tests out for an initial acquisition in Appendix 15 of SOP 50 10 8.1.
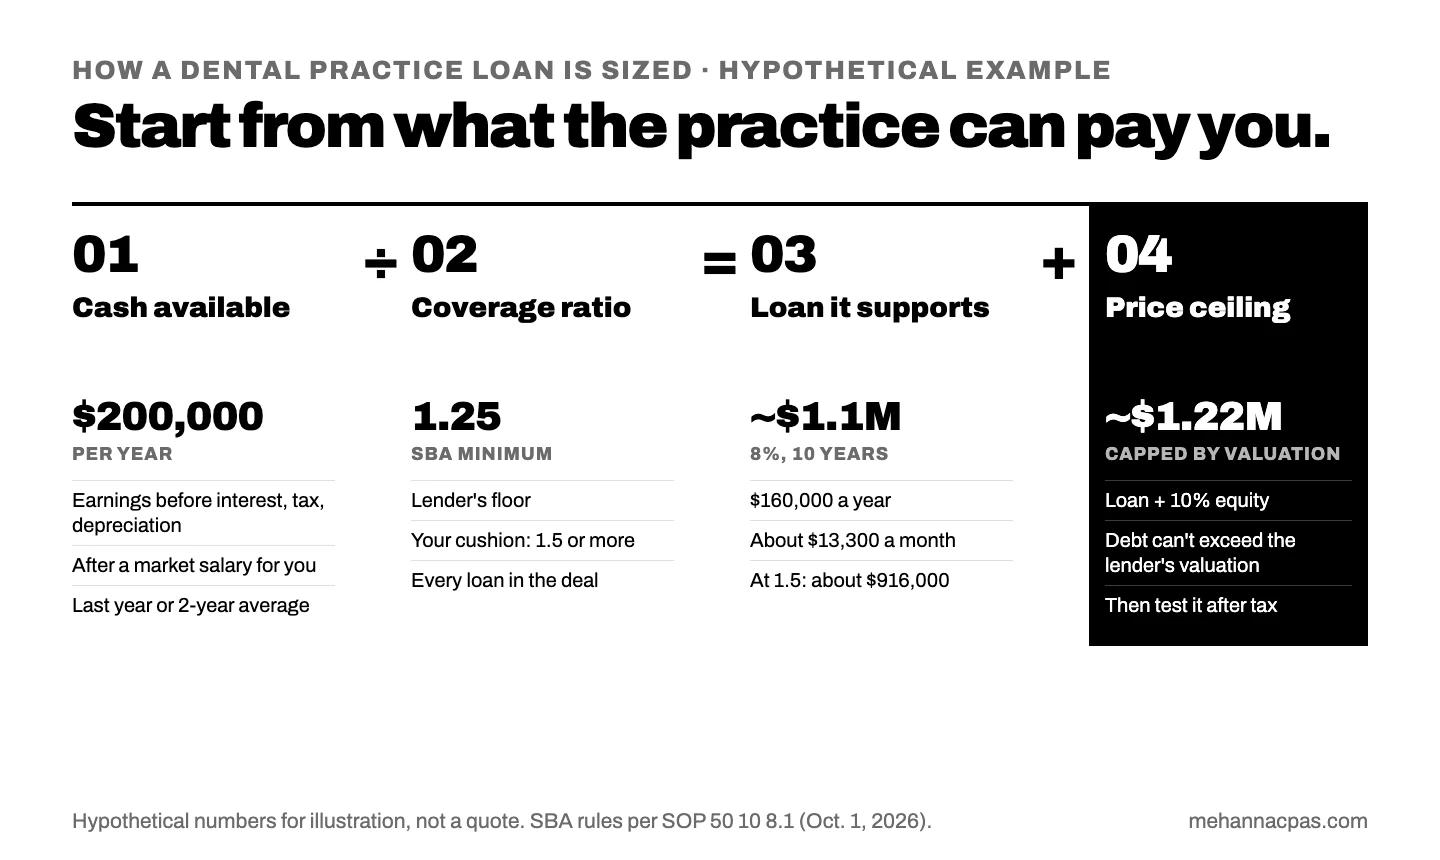
1. Debt coverage. The lender takes the practice’s earnings before interest, taxes, depreciation and amortization, adjusted for the seller’s personal costs and owner pay, and divides it by every loan payment after closing. For an SBA initial acquisition the ratio must be at least 1.25, measured on the last fiscal year or the average of the last two, and post-closing projections can’t be used to meet it. Any adjustment to owner pay has to leave the owners able to cover their own obligations.
2. The valuation cap. For an SBA change of ownership, total debt, including a seller note that isn’t on full standby, can’t exceed the business valuation, which the lender orders. Anything you pay above it comes from your own cash.
3. Equity. An initial acquisition needs at least 10% of the total project cost as equity, and it can’t be reduced. Cash you didn’t borrow counts in full. A seller note on full standby, meaning no principal or interest payments for the life of the 7(a) loan, can count, but together with other standby debt and small minority investors it can supply no more than half of the required injection.
Here’s how that plays out with round, hypothetical numbers. Say the practice shows $200,000 a year of cash available for debt service after a market salary for your dentistry. At 1.25 coverage, payments can reach $160,000 a year, about $13,300 a month, which at 8% over ten years supports a loan of roughly $1.1 million. Add the 10% equity and the project tops out around $1.22 million, and only if the lender’s valuation agrees.
How we test a practice acquisition loan with dental buyers
We start from what the practice can pay you, then work back to the loan and the price. A practice acquisition analysis is a project we scope and price on a call. The steps:
- Rebuild the earnings from three years of returns and P&Ls, tied to the practice management system and bank deposits. Reading those statements line by line is covered in how to read your practice’s financial statements.
- Pay you first. Replace the seller’s pay with what a market associate would earn for the same dentistry, and remove personal and one-time costs.
- Run the bank’s test at the real rate, term and fees, with every loan in the deal: practice, equipment, seller note.
- Run your test with a wider cushion, your household budget and your student loan payments.
- Run it after tax for years one to five, because the deductions that help in year one don’t repeat.
- Stress it. What happens if collections fall 10% in the transition year, or the fee schedule you’re credentialed at pays less than the seller’s?
After closing, the same three people stay on it all year, with projections and a text before you sign anything big.
Buyers rarely borrow too much because the bank made a mistake. The bank’s test is built to get the bank repaid. The gap shows up in the owner’s column: a loan that clears 1.25 on paper can still leave less take-home pay than the associate job did, once the student loans, a real salary and the tax on principal are in the same spreadsheet. We’d rather find that before the offer than in the first April.
How much dental practice can I afford?
Less than the lender’s maximum, and the gap is your safety margin. Use three numbers, not one:
| The number | What it answers | How to get it | Hypothetical example |
|---|---|---|---|
| The lender’s maximum | Will the bank lend? | Cash available ÷ 1.25, turned into a loan at the quoted rate and term | About $1.1 million |
| Your comfortable number | Can the practice absorb a bad year? | Same math with a wider cushion, such as 1.5 | About $916,000 |
| Your after-tax number | Will you take home enough in years two to five? | Payments compared with after-tax cash, once year-one write-offs are used up | Depends on the allocation and your tax bracket |
The examples use $200,000 of cash available at 8% over ten years. Your numbers will differ with the practice, the rate and your household.
How much do lenders lend for a dental practice?
Lenders lend what the practice’s cash flow supports, up to the valuation and the program’s limits. The ADA notes that banks see dental practices as safe loans and that many finance the full price plus working capital (ADA). That’s the reason the approval amount says little about whether the price is right.
Is an SBA loan for a dental practice the better choice?
Not automatically. An SBA 7(a) loan has published rules: at least 10% equity, 1.25 coverage on historical results and a rate that can’t exceed the SBA maximum, which for loans above $350,000 is the base rate plus 3% (SBA). A conventional dental lender may ask for less equity and price differently. Compare the full cost, including fees, prepayment terms and the personal guaranty, side by side.
Can the seller finance part of the purchase?
Yes, and it changes the math in two ways. If the note gets paid while your bank loan is outstanding, its payments count in the coverage test. If it sits on full standby under an SBA loan, it can cover up to half of your equity, but the seller waits years for the money, so expect that in the negotiation.
Have a pre-approval and a practice in mind? Walk through the loan, your salary and the after-tax cash before the letter of intent.
Five tax rules that change what the loan really costs
The interest is usually deductible, the principal never is, and how you spend the loan money matters. These are the rules worth knowing before closing.
1. Interest on a practice loan is generally deductible
A business that meets the gross receipts test, and isn’t a tax shelter, is generally a small business taxpayer and isn’t subject to the business interest limit of section 163(j) (IRS, Instructions for Form 8990). For 2026 the test is average annual gross receipts of $32 million or less over the prior three years (Rev. Proc. 2025-32). That covers almost every privately owned practice. Large groups and DSO-affiliated structures should check it.
2. Interest follows what the money paid for
Interest is allocated by how the loan proceeds are used, not by what secures the loan (Treas. Reg. 1.163-8T). Loan money that lands in a personal account and mixes with other cash can end up traced to personal spending, which makes that share of the interest nondeductible. Keep the proceeds, including a home equity line used for your equity, in a separate business account and spend them directly on the practice. The rules let you treat a payment made within 15 days of the deposit as made from the loan.
3. Principal isn’t deductible, and goodwill is slow
You deduct the purchase through depreciation and amortization, not through the loan payments. Goodwill, the patient base and a non-compete are generally amortized over 15 years (IRS), while the loan usually runs 10. In a hypothetical $1 million loan at 8% over ten years with $850,000 allocated to intangibles, the yearly amortization is about $56,700, while principal runs from about $68,000 in year one to about $94,000 in year five. The difference is paid with income you’ve already been taxed on. That’s why the price allocation matters as much as the price.
4. Year-one write-offs don’t repeat
Equipment in the deal can often be deducted in year one through bonus depreciation or Section 179, as our Section 179 guide for dental equipment explains. That lowers the first year’s tax, and then the deduction is gone while the payments continue. A large first-year loss can also run into the excess business loss limit, $256,000 ($512,000 joint) for 2026 (Rev. Proc. 2025-32). Model several years, not just the first.
5. A seller note has to carry enough interest
If the seller finances part of the price and the note’s rate is below the IRS minimum, generally tied to the applicable federal rate, part of what you pay as principal is treated as interest for tax purposes (IRS Publication 537). Set a rate that clears the minimum when you agree the note.
Dental practice loan checklist
Use this table to see what to collect, when, and why each item matters to the loan. Every row comes from the sections above.
| Item | When | Where it comes from | What it protects |
|---|---|---|---|
| Quotes from 3+ dental lenders | Before looking | Lenders | A real rate, term and equity requirement |
| Last two years of earnings, adjusted | Before the offer | Seller’s returns and P&Ls | The coverage test the SBA uses |
| Market salary for your dentistry | Before the offer | Your CPA, associate offers | A loan that still pays you |
| Household budget and student loan payments | Before the offer | You | The global 1 to 1 test, and your comfort |
| Equity source (cash, seller standby note) | Before the letter of intent | You, the seller | The 10% injection and its limits |
| Lender’s valuation | During underwriting | Independent appraiser ordered by the lender | Not paying above what the debt can cover |
| Price allocation | Before the purchase agreement | Purchase agreement, Form 8594 | Deductions in years one to five |
| Seller note rate | When the note is agreed | Attorney and CPA | No interest recharacterized by the IRS |
| Separate account for loan proceeds | Before closing | Your bank | Deductible interest |
| Five-year after-tax projection | Before closing | Your CPA | Knowing year two won’t surprise you |
Mistakes we’d avoid
Most loan problems start with a number nobody checked against the owner’s own life. The ones we’d steer you away from:
- Treating the pre-approval as your budget. It tells you what the bank will accept, not what leaves you a good year.
- Running coverage without your salary. A practice that only clears 1.25 if you take no pay can’t afford the loan.
- Forgetting the second loan. Equipment financing and a seller note that’s paid currently count in the coverage test, and in your month.
- Mixing the loan money with personal cash. It can cost you part of the interest deduction.
- Planning on year one’s tax picture. Bonus depreciation and Section 179 help once. The payments keep coming.
What changed for 2026
The SBA rewrote its acquisition rules effective October 1, 2026, and the 2026 tax thresholds moved. The changes that matter for a dental practice acquisition loan:
- SOP 50 10 8.1 replaced SOP 50 10 8 on October 1, 2026 (SBA Information Notice 5000-880695).
- Initial acquisitions need debt coverage of at least 1.25, measured on the last year or a two-year average, and projections can’t be used to meet it (SBA SOP 50 10 8.1).
- Standby seller notes, other standby debt and minority investors under 20% together can provide no more than half of the required equity.
- Extra acquisition debt that isn’t on full standby and is interest-only must be tested as if it amortized over no more than 10 years.
- A seller note in an SBA change of ownership can be refinanced only after it has been in place and current for 36 months.
- On the tax side, the 2026 gross receipts test for the business interest limit is $32 million and the excess business loss threshold is $256,000 ($512,000 joint) (Rev. Proc. 2025-32).
How to tell whether the loan was the right size
At twelve months, three numbers say it: coverage, your take-home pay and cash on hand. The practice should cover all its loan payments with room above what the lender required, pay you at least what an associate would earn for the same dentistry, and hold a few months of operating cash without drawing on a line of credit. If one of those only works because you skipped your own salary, find which assumption broke: patients who left with the seller, a lower fee schedule or costs that weren’t in the summary. Year-round projections and planning calls after a purchase are part of The Treatment Plan.
Frequently asked questions
How much do I need to put down on a dental practice loan?
With an SBA 7(a) loan for a first acquisition, at least 10% of the total project cost, plus anything above the lender’s valuation. Up to half of that 10% can come from a seller note on full standby. Conventional dental lenders set their own requirements, and some finance the full price, so compare at least three.
Do student loans affect how much practice I can buy?
Yes. SBA lenders test that the owners’ pay covers their personal obligations, and conventional lenders look at your debts too. Student loan payments reduce what’s left for the practice loan and for your household. Put them in the model from the start, not after the pre-approval.
Can I use a home equity line for the down payment?
Sometimes, depending on the lender and the program’s rules on borrowed equity. For tax purposes, interest follows how the money is used, so a home equity line spent on the practice can be business interest. Keep that money in a separate business account and document where it went.
What rate should I expect on a dental practice loan?
It depends on the market and the lender. SBA 7(a) rates are negotiated but can’t exceed the SBA maximum, which is the base rate plus 3% for loans above $350,000. Conventional lenders price on their own terms. Compare the annual cost including fees, not only the headline rate.
What happens if the lender’s valuation comes in below the price?
Under an SBA loan, total debt can’t exceed the valuation, so the gap has to come from your cash or a seller note on full standby, or the price has to come down. Treat a low valuation as information about the price, not only as a financing problem.
Are loan payments tax deductible?
The interest generally is, for a practice under the $32 million gross receipts test in 2026, if the money was used for the practice. The principal isn’t. You recover the purchase price through depreciation and amortization instead, on schedules that usually run slower than the loan.
Glossary
| Term | Meaning |
|---|---|
| Debt service coverage | Earnings divided by all loan payments. The SBA requires at least 1.25 for an initial acquisition. |
| Cash available for debt service | The practice’s earnings after a market salary for your dentistry, before loan payments. |
| Equity injection | Your own money in the deal. At least 10% of the project cost for an SBA initial acquisition. |
| Full standby | A note that receives no principal or interest payments for the life of the SBA loan. |
| Business valuation | The lender’s independent estimate of the practice’s value. It caps total debt under an SBA loan. |
| Global cash flow | The lender’s test that the owners’ income also covers their personal obligations. |
| Applicable federal rate (AFR) | The minimum interest rates the IRS publishes monthly, used to test seller notes. |
| Amortization (tax) | Deducting goodwill and other intangibles evenly over 15 years. |
Sources
- U.S. Small Business Administration, SOP 50 10 8.1, Lender and Development Company Loan Programs (effective October 1, 2026), Appendix 15: 1.25 coverage on historical earnings, projections not allowed, global 1 to 1, 10% equity, standby limits, debt capped at valuation, 10-year amortization test, 36-month seller note refinance.
- U.S. Small Business Administration, Information Notice 5000-880695, Issuance of SOP 50 10 8.1 (2026).
- U.S. Small Business Administration, 7(a) loans: $5 million maximum, uses, monthly repayment from cash flow.
- U.S. Small Business Administration, 7(a) terms, conditions and eligibility: maturity limits and maximum interest rates.
- IRS, Rev. Proc. 2025-32 (2025): 2026 gross receipts test ($32 million) and excess business loss threshold ($256,000 / $512,000).
- IRS, Instructions for Form 8990 (2025): small business taxpayers are not subject to the section 163(j) limitation.
- Electronic Code of Federal Regulations, 26 CFR 1.163-8T: interest allocated by use of the proceeds, 15-day rule.
- IRS, Intangibles: 15-year amortization of goodwill and other section 197 intangibles.
- IRS, Publication 537, Installment Sales (2025): unstated interest and the applicable federal rate on seller financing.
- American Dental Education Association, Dentists of Tomorrow 2025 (January 2026): average education debt of $297,800 for graduates with debt.
- American Dental Association, Talk to 3 banks: the first step in buying a dental practice: lender views and financing of the full price.