
S corp vs. LLC is not really a choice between two entities. An LLC or PLLC is how your state lets you organize the practice; an S corporation is a federal tax election that an LLC, PLLC or professional corporation can make on Form 2553. For a dentist, the real question is how the practice entity should be taxed.
- Most dental practices are a PLLC or a PC under state law. The S election changes the tax, not the liability protection.
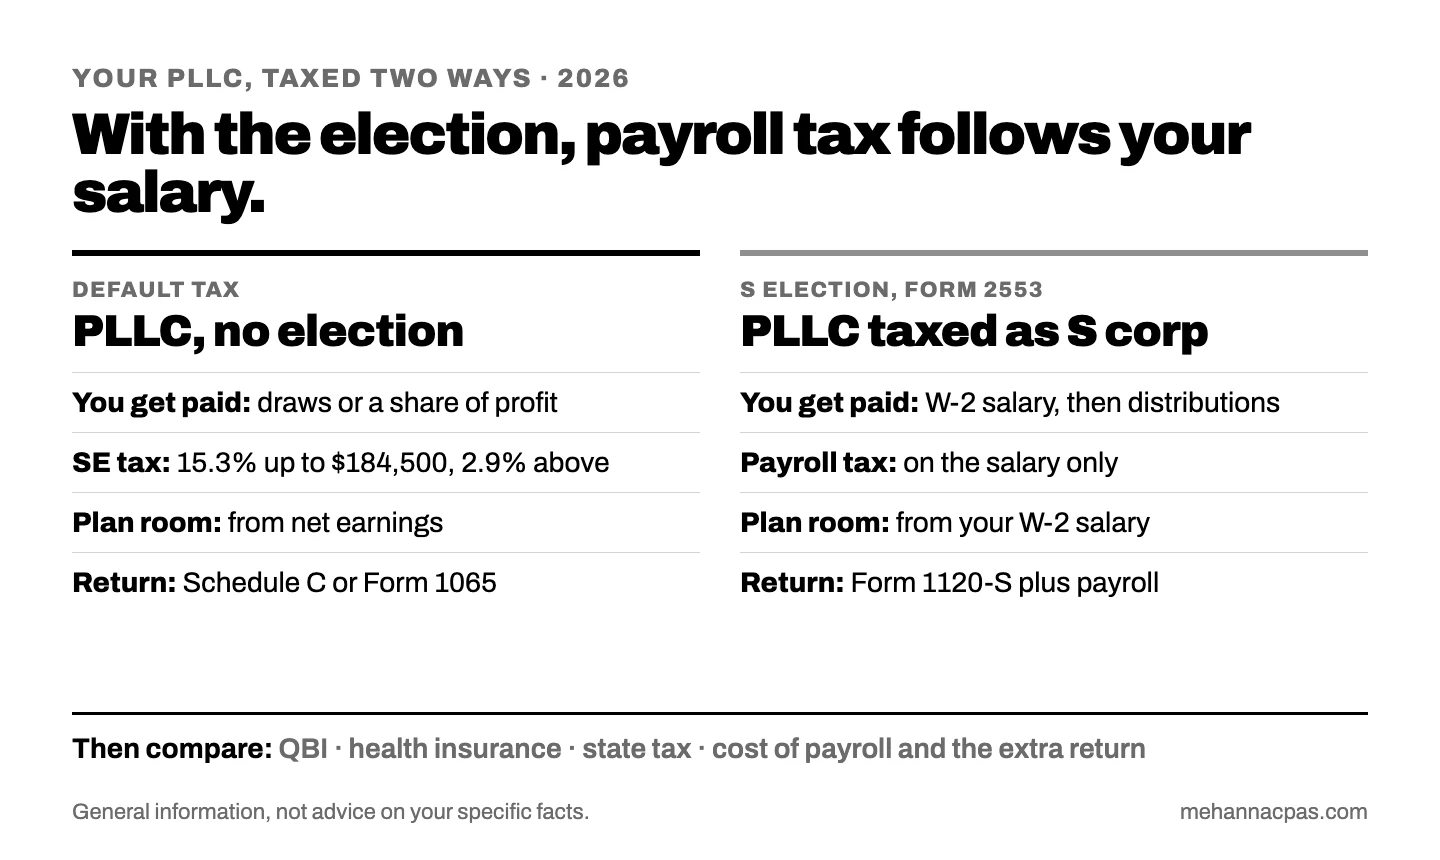
- Without the election, self-employment tax of 15.3% applies to the owner’s net earnings up to the 2026 wage base of $184,500, and 2.9% above it. With it, payroll tax applies only to the W-2 salary.
- For dentists, the S corp does not unlock the QBI deduction: dentistry is a specified service, and above $553,500 of joint taxable income (2026) there is no deduction either way.
- The election also moves your retirement plan room, your health insurance deduction and, in many states, your state tax options. They belong in the same comparison.
- What we see most in dental practices: an election made because a colleague did it, with nobody running the numbers on salary, the retirement plan and the state return together.
The practice is profitable, the return showed a big self-employment tax line, and two colleagues at the last study club both said the same thing: “You need to be an S corp.” The attorney who formed your PLLC never mentioned it. Your last accountant filed what you sent. Now you are wondering whether you have been in the wrong structure for years.
This guide answers the question the way it actually works for a dental practice owner: what an LLC, a PLLC and an S corporation each are, how you get paid in each, where the S election helps and where it costs you, and when to make it.
What is the difference between an S corp and an LLC?
An LLC is a legal entity formed under state law; an S corporation is a tax status chosen with the IRS. The two answer different questions. The LLC (or PLLC, or professional corporation) decides who is liable for what. The S election decides how the profit is taxed and how you pay yourself.
By default, the IRS treats a one-owner LLC as part of the owner’s personal return and an LLC with two or more members as a partnership (IRS). An eligible entity that files a timely Form 2553 is treated as a corporation from the effective date of the S election and doesn’t need a separate Form 8832 (Instructions for Form 2553). So “LLC or S corp” is usually “LLC taxed by default, or LLC taxed as an S corp”.
| PLLC or LLC, default tax | PLLC or LLC taxed as an S corp | C corporation | |
|---|---|---|---|
| What it is | State-law entity; taxed as you (one owner) or as a partnership | Same entity plus a federal election on Form 2553 | A corporation taxed on its own profit |
| How you get paid | Draws (one owner) or a share of profit plus payments for services (partners) | W-2 salary through payroll, then distributions | W-2 salary, then dividends |
| Social Security and Medicare | Self-employment tax on the owner’s net earnings | Payroll tax on the salary only | Payroll tax on the salary |
| Federal return | Your Schedule C, or Form 1065 for partners | Form 1120-S, plus payroll filings | Form 1120, plus payroll filings |
| Liability protection | Set by state law | Unchanged by the election | Set by state law |
The C corporation column is there for completeness. It pays a flat 21% on its own profit (26 U.S.C. 11), and what it pays you as dividends is taxed again on your return, which is why few owner-run dental practices use it.
Dentist PLLC vs. S corp: which one do I have?
Possibly both. Many states require licensed professionals to organize as a professional entity, so a dental practice entity is often a PLLC or a PC. Check two things: the formation papers from your state (that is the PLLC or PC), and whether the practice files Form 1120-S and runs payroll for you (that is the S election). Your last return answers the second question in a minute.
Who should look at an S election, and who can skip it?
The election is worth a real look when the practice’s profit runs well above what your own clinical and management work would earn as a salary. In dental practices, that usually means one of these:
- You own a profitable practice as a single-member PLLC and pay self-employment tax on all of the profit.
- You have associates or a strong hygiene department, so a growing share of the profit is not produced by your own hands.
- You are about to buy a practice and are setting up the entity before closing.
- You and a partner own a PLLC taxed as a partnership, and each of you pays self-employment tax on your full share.
You can probably skip it, or wait, if the practice is new and profit is still thin, if nearly all of the profit is your own production and a reasonable salary would absorb it, or if you are an associate on a W-2. In that last case, this question belongs to the day you buy in or open your own office.
Why does the choice matter for a dental practice?
Because it decides which part of the profit carries Social Security and Medicare tax, and it moves three other numbers at the same time.
Self-employment tax. Without the election, the owner pays 15.3% (12.4% Social Security plus 2.9% Medicare) on net earnings up to $184,500 for 2026, and 2.9% above that (IRS). An extra 0.9% Medicare tax applies above $200,000, or $250,000 on a joint return (SSA 2026 fact sheet). With the election, those taxes apply to your W-2 salary, and the profit above it goes out as distributions without them. The saving, when there is one, comes from the profit above a reasonable salary, so the bigger that gap, the more the election can matter.
The QBI deduction. You will read that an S corp “unlocks” the 20% qualified business income deduction. For a dentist it doesn’t work that way. Dentistry is a health service, a specified service under the tax code, and for 2026 the deduction phases out between $403,500 and $553,500 of taxable income on a joint return (Rev. Proc. 2025-32). Above that range there is no deduction for the practice income, with or without the election. Inside it, the salary you pay yourself changes the result, and S corp wages are not qualified business income (IRS QBI FAQs), so it has to be run both ways.
Your retirement plan. In an S corporation, plan contributions for you are figured on your W-2 salary, and the employer contribution to an owner-only 401(k) is limited to 25% of it (IRS). Without the election, the base is your net earnings from self-employment. A low salary saves payroll tax and also shrinks what the plan can take. For 2026 the deferral limit is $24,500 and the total defined contribution limit is $72,000 (IRS Notice 2025-67).
Your health insurance. As a more-than-2% S corporation shareholder, the practice has to pay or reimburse your premiums and report them as wages on your W-2 for you to take the self-employed health insurance deduction (IRS FS-2008-25). It is a setup step, and it is easy to miss in year one.
When should you become an S corp, and when should you wait?
For a calendar-year practice, file Form 2553 by March 15 for the election to cover the whole year. The rule is no more than 2 months and 15 days after the start of the tax year, or any time during the year before (Instructions for Form 2553). For a new entity, the clock starts on its first day. An election filed after the deadline generally applies from the next year.
Missed it? Relief for a late election is available in many cases when there was reasonable cause, generally if Form 2553 is filed within 3 years and 75 days of the intended effective date (Instructions for Form 2553; Rev. Proc. 2013-30). That is a fix, not a plan.
The triggers we watch: profit that has grown well past what your own dentistry would earn as a salary, a new associate or hygiene day, a practice purchase, and a plan to open or redesign a retirement plan. The honest reasons to wait: a first year with little profit, a purchase that will reshape the numbers within months, or a state that taxes S corporations in a way that eats the federal benefit.
Think before you elect, because leaving is slower than joining. Revoking the election takes the consent of shareholders holding more than half the shares, and after a termination the corporation generally can’t elect again for five years without IRS consent (26 U.S.C. 1362).
How we decide entity structure with dental practices
We run the practice both ways on real numbers before anyone files a form. The steps:
- Read what you have. Formation papers, the last two returns, payroll reports and who owns what. Many owners are already a PLLC and only need to decide how it is taxed.
- Split the profit. From the practice management system, separate your own production from associates and hygiene. That split drives the reasonable salary for an S corp dentist, and the salary drives everything else.
- Project both versions: self-employment tax or payroll tax, QBI, retirement plan room, health insurance, state tax and the extra cost of payroll and a separate return.
- Check the state. Some states tax S corporations or charge entity-level fees; many let an S corporation or partnership elect to pay state income tax at the entity level, which the IRS has said the entity can deduct (IRS Notice 2020-75).
- Set it up cleanly if the numbers say yes: Form 2553 on time, payroll for you from the first period, premiums on your W-2, and new estimated payments for the year.
- Revisit it at the planning calls through the year. The same three people stay on it, and you text before you sign anything that changes the practice’s shape.
The usual story is an election made because a colleague made one, with no salary study and no look at the retirement plan. The second most common is the opposite: a PLLC that has been profitable for years, still paying self-employment tax on all of it, because nobody asked. Both are fixable. Both are easier to fix before the year closes than after the return is filed.
Should a dentist be an S corp? How to decide for your practice
A dentist should consider the S election when the profit left after a defensible salary is large enough to cover the extra cost and paperwork with room to spare. There is no universal break-even number for an S corp for dentists, because it depends on your salary, your state and your plan design. Use this as a first read.
| Your situation | Leans toward the S election | Leans toward staying as is |
|---|---|---|
| Solo owner, profit mostly your own production | Profit well above a market salary for your work | A reasonable salary would absorb most of the profit |
| Owner with associates or a strong hygiene department | Much of the profit is produced by others | Rarely; this is the classic case for the election |
| Two-dentist PLLC taxed as a partnership | Each partner pays self-employment tax on a full share | Profit splits that don’t follow ownership (an S corp can’t do that) |
| Startup or first year after a purchase | Profit already strong from day one | Thin or uncertain profit; revisit next year |
| Owner who wants a large retirement plan | Salary set high enough for the plan design | A low salary that would cap the plan |
Should I be an S corp if I am the only owner?
Often yes, once profit clearly exceeds what your own clinical and management work would earn. A single-member PLLC is already treated as a separate entity for employment tax (IRS), so adding payroll for yourself is a mechanical step. The open question is the salary, not the paperwork.
Dentist LLC or S corp when two dentists own the practice?
By default, a two-owner PLLC is a partnership, and each owner who works in the practice generally pays self-employment tax on their share of the profit; the limited-partner exception is narrow (26 U.S.C. 1402). An S election puts each owner on a salary. The trade-off: an S corporation has one class of stock, so profit follows ownership and can’t be split by production the way a partnership agreement can.
What if my spouse and I own the PLLC together?
An LLC owned by two spouses is generally a partnership with its own return. In a community property state, the IRS accepts treating an entity owned only by spouses as community property either as a disregarded entity or as a partnership (Rev. Proc. 2002-69). The qualified joint venture election for spouses does not apply to a business held in an LLC (IRS).
Not sure how your practice should be taxed? Bring your last return and your current P&L, and leave the call knowing where you stand.
The costs of an S corp nobody mentions
The payroll tax side is the part everyone quotes. These are the other lines on the ledger.
1. A separate return
The practice files Form 1120-S and issues you a Schedule K-1 (IRS). That is more preparation work than a Schedule C, every year.
2. Payroll for you, every pay period
Your salary runs through payroll with withholding and quarterly employment tax filings. A salary paid once in December, or not at all, is the pattern the reasonable compensation rules exist for.
3. State taxes and fees
Some states and cities tax S corporations or charge entity fees that reduce the federal benefit. Check your state before you elect, not after.
4. Health insurance setup
Premiums have to be paid or reimbursed by the practice and reported on your W-2 to keep the deduction. Premiums left in your personal name and paid personally are a common year-one miss.
5. Assets inside the corporation
Distributing property such as equipment or a building out of an S corporation can be a taxable event at its value. If the practice will own real estate, decide where it sits before it is bought.
S corp vs LLC checklist for dental practice owners
Use this to see what to review and when. A rough estimate is enough to start.
| Item | Fits you if | Deadline | What to bring |
|---|---|---|---|
| Entity check | You are not sure what the practice is | Any time | State formation papers, last return |
| Both-ways projection | Profit is well above a market salary for your work | Before you file Form 2553 | Year-to-date P&L, production by provider |
| Form 2553 | The numbers say elect, calendar-year practice | March 15 for the full year | EIN, all owners’ consents |
| Late election relief | You meant to elect and missed it | Within 3 years and 75 days of the intended date | Proof of intent, reasonable cause |
| Owner payroll | The election is in effect | From the first pay period | Salary study, payroll provider |
| Health insurance on your W-2 | You own over 2% and want the deduction | Before W-2s are produced | Premium statements |
| State entity tax election | Your state offers one and your income is high | State-specific | State return, estimates |
Mistakes we’d avoid
Most entity mistakes come from deciding on one number instead of the whole return. The ones we’d steer you away from:
- Electing because a colleague did. Their salary, state and plan design are not yours.
- Electing to “get” the QBI deduction. For dentists above the 2026 range there is none either way; inside it, salary can shrink it.
- Setting a very low salary. It invites reclassification and caps your retirement plan. See how the number is built in our guide to S corp reasonable salary for dentists.
- Keeping contracts in your own name. Payer agreements, the merchant account and the lease should be in the practice entity’s name, and your pay should come through payroll, not through endorsed checks.
- Forgetting estimates. Salary withholding replaces part of your quarterly payments, but distributions still need planning. Here is how to set aside the right number for estimated taxes.
What changed for 2026
Several numbers that drive the comparison moved this year.
- The Social Security wage base is $184,500 for 2026 (IRS; SSA).
- On a joint return, the QBI phase-out for a specified service such as dentistry runs from $403,500 to $553,500 of taxable income (Rev. Proc. 2025-32). The deduction itself no longer has a 2025 end date: the 2025 budget law (P.L. 119-21) made it permanent.
- Retirement plan limits rose to $24,500 for 401(k) deferrals and $72,000 in total (IRS Notice 2025-67).
How to tell whether your entity choice is working
You can show three things on one page: the projection that justified the structure, the salary study behind your W-2, and the retirement plan room at that salary. Each year, compare the payroll tax and state tax you actually paid with what the default structure would have cost on the same profit. If the gap has narrowed, because profit fell or your salary had to rise, the structure is due for another look. If nobody can produce the projection, the election is a habit, not a decision.
This is the kind of work a dental CPA does that a general CPA usually won’t. Entity structure is reviewed with the projections all year as part of The Treatment Plan.
Frequently asked questions
Do I need to form a new company to become an S corp?
Usually not. An existing PLLC, LLC or professional corporation that meets the eligibility rules can file Form 2553 and keep its legal form. The state entity stays the same; only the federal tax treatment changes from the effective date of the election.
Does an S corp give more liability protection than an LLC?
No. Liability protection comes from the state-law entity and from your malpractice coverage, not from the tax election. A professional entity generally does not shield you from claims about your own clinical work, which is what malpractice insurance is for.
Can I switch back from an S corp to an LLC?
You can revoke the election with the consent of shareholders holding more than half the shares. After a termination, the entity generally can’t elect S status again for five years without IRS consent, so the decision deserves a projection first.
Is an S corp worth it for a new dental practice?
Sometimes. If first-year profit is thin, the payroll and return costs can outweigh the payroll tax difference, and a salary can’t exceed what you take out anyway. Many owners revisit it once the practice has a full year of numbers.
Does the S election change my state taxes?
It can. Some states tax S corporations or charge entity fees, and many let an S corporation or partnership pay state income tax at the entity level, which can matter when your personal state tax deduction is limited. Check the state before electing.
Glossary
| Term | Meaning |
|---|---|
| PLLC / PC | A professional limited liability company or professional corporation: the state-law form many states require for licensed professionals. |
| S election | The choice, made on Form 2553, to have an eligible entity taxed as an S corporation. |
| Self-employment tax | Social Security and Medicare tax paid by owners who are not on payroll: 15.3% up to the wage base, 2.9% above it. |
| Wage base | The yearly cap on earnings subject to Social Security tax: $184,500 for 2026. |
| Distribution | Profit paid to an S corporation owner as an owner, without Social Security and Medicare tax. |
| Specified service | A category under the QBI rules that includes health, and so dentistry. Its deduction phases out at higher incomes. |
| Disregarded entity | A one-owner LLC that the IRS treats as part of the owner’s own return for income tax. |
Sources
- IRS, Instructions for Form 2553 (2020): who may elect, deadline, no Form 8832 needed, late election relief.
- IRS, Rev. Proc. 2013-30 (2013): relief for late S corporation elections.
- IRS, Limited liability company (LLC): default classification, employment tax treatment.
- IRS, S corporations: Form 1120-S and employment tax filings.
- IRS, Self-employment tax: 15.3% rate and the 2026 wage base.
- Social Security Administration, 2026 COLA fact sheet (2025): wage base and additional Medicare tax.
- IRS, Rev. Proc. 2025-32 (2025): 2026 QBI thresholds.
- IRS, Section 199A deduction FAQs: specified services, S corporation wages.
- IRS, One-participant 401(k) plans: contributions based on compensation.
- IRS, Notice 2025-67 (2025): 2026 retirement plan limits.
- IRS, FS-2008-25 (2008): health insurance for 2% shareholders on the W-2.
- IRS, Notice 2020-75 (2020): entity-level state income taxes paid by partnerships and S corporations.
- IRS, Rev. Proc. 2002-69 (2002): spouse-owned entities in community property states.
- IRS, Election for married couples unincorporated businesses: qualified joint ventures exclude LLCs.
- U.S. Code, 26 U.S.C. 1362: revocation and the five-year wait.
- U.S. Code, 26 U.S.C. 1402: partners’ net earnings from self-employment, limited partner exception.
- U.S. Code, 26 U.S.C. 11: 21% corporate tax rate.